Understanding Reverse Mortgages: A Comprehensive Overview
As homeowners age, many seek financial solutions that allow them to leverage their home equity while mitigating the cost of traditional mortgages. One such option that has gained traction is the reverse mortgage. This financial product can provide seniors with a valuable income stream, but understanding its mechanics is crucial before making any decisions. Through this article, we’ll delve into the intricacies of reverse mortgages, their benefits and drawbacks, the necessary eligibility criteria, and much more to help you navigate this complex topic.
When exploring options, reverse mortgages offer comprehensive insights that can empower homeowners over the age of 62 to make informed choices about their financial future.
What is a Reverse Mortgage?
A reverse mortgage is a financial product designed for homeowners aged 62 and older that allows them to convert part of the equity in their homes into cash. Unlike traditional mortgages where the borrower makes monthly payments, in a reverse mortgage, the lender pays the homeowner based on the home's equity. This can help seniors cover living expenses, healthcare costs, or even travel, without the burden of monthly mortgage payments.
How Reverse Mortgages Work
Here's a breakdown of how reverse mortgages function:
- Equity Conversion: Homeowners can access a portion of their equity, which is calculated based on the home’s appraised value, the borrower's age, and current interest rates.
- No Monthly Payments: Homeowners are not required to make monthly payments. The loan is repaid when the homeowner sells the house, moves out, or passes away.
- Loan Amount: The amount available through a reverse mortgage can vary significantly. Typically, it can range from 40% to 60% of the home's value depending on the factors mentioned above.
Eligibility Criteria for Reverse Mortgages
To qualify for a reverse mortgage, applicants must meet specific criteria:
- Be at least 62 years old
- Own the home outright or have a low remaining mortgage balance
- Reside in the home as their primary residence
- Be able to demonstrate financial stability to meet other requirements (such as property taxes, insurance, and maintenance)
Pros and Cons of Reverse Mortgages
Like any financial product, reverse mortgages come with both advantages and drawbacks that seniors should consider before proceeding.
Financial Advantages of Reverse Mortgages
- Increased Cash Flow: Seniors can access funds to cover daily living expenses, home repairs, or medical bills.
- No Monthly Payments: Homeowners can enjoy peace of mind without the pressure of monthly mortgage payments.
- Preservation of Assets: Seniors can maintain ownership of their home while still accessing cash, allowing them to preserve other savings or investments for emergencies.
Potential Risks and Challenges
- Debt Accumulation: Interest on the loan accumulates over time, which can lead to a significant reduction in home equity.
- Potential for Foreclosure: If homeowners fail to pay property taxes, insurance, or maintain the property, the lender may foreclose on the home.
- Inheritance Issues: The property may not be passed on to heirs as expected, as reverse mortgages must be repaid upon the homeowner's passing.
Common Misconceptions about Reverse Mortgages
Several myths surround reverse mortgages that can lead to confusion:
- You Lose Ownership: Many believe that obtaining a reverse mortgage means they surrender ownership of their home; this is untrue. The homeowner retains the title.
- Reverse Mortgages Are Only for Financially Strapped Seniors: In reality, many seniors have stable financial situations but choose to leverage their equity for various reasons.
Choosing the Right Reverse Mortgage Program
Given the variety of reverse mortgage options available, it’s essential to conduct thorough research to find the best fit for your needs.
Types of Reverse Mortgages Explained
- Home Equity Conversion Mortgage (HECM): The most common type, insured by the Federal Housing Administration, allowing seniors access to a significant portion of their home equity.
- Proprietary Reverse Mortgages: These are private loans not insured by the government, typically for higher-value homes.
- Single-Purpose Reverse Mortgages: Offered by some state and local government agencies, these loans are designed for a specific purpose, such as home repairs or property taxes.
How to Compare Reverse Mortgage Offers
When comparing various reverse mortgage offers, consider the following factors:
- Interest Rates: Look at both fixed and adjustable rates.
- Fees and Costs: Evaluate origination fees and closing costs which can vary significantly.
- Borrower Protections: Ensure that the lender has strong consumer protections in place.
Considerations for Selecting a Lender
Choosing the right lender involves careful scrutiny:
- Reputation: Research lender reviews and their standing with the Better Business Bureau.
- Experience: Opt for lenders who specialize in reverse mortgages and have a track record of transparency and reliability.
Navigating the Reverse Mortgage Process
Understanding the process of applying for a reverse mortgage can significantly ease any anxiety associated with it.
Steps to Apply for a Reverse Mortgage
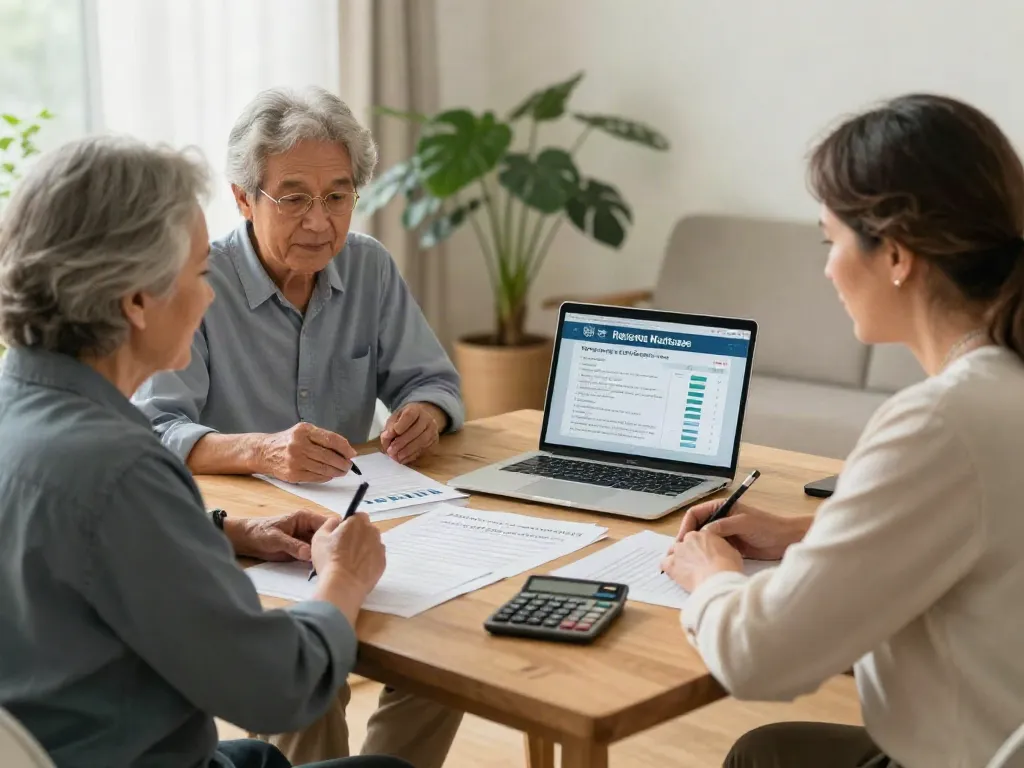
- Consult a Housing Counselor: A mandatory counseling session can help clarify the product and its implications.
- Gather Documentation: Compile necessary documents such as income statements, tax returns, and property documents.
- Submit Application: Once documents are in order, submit your application through the lender of your choice.
Understanding Required Documentation
Documentation needed typically includes:
- Proof of age
- Title deed or deed of trust
- Financial statements, including income and expenses
- Homeowner’s insurance details
What to Expect During the Approval Process
The approval process can take several weeks. During this time:
- The lender will appraise the home to determine its current market value.
- A thorough review of your financial situation will take place to ensure you meet eligibility requirements.
Future Trends in Reverse Mortgages: What to Expect in 2026
The landscape of reverse mortgages is continually evolving. As we look forward to 2026, several trends are emerging that may reshape this financial tool for seniors.
Technological Innovations in Reverse Mortgages
New technologies are streamlining the application process, making it more accessible and efficient for seniors.
Changes in Regulations Affecting Seniors
Regulatory shifts may alter the terms and conditions associated with reverse mortgages, impacting how they are marketed and structured.
Market Predictions and Their Implications
As the aging population increases, the demand for reverse mortgages is expected to rise. This can influence market rates and the availability of various products.
How Will Reverse Mortgages Evolve?
Looking ahead, we can anticipate a broader range of products tailored specifically to different financial needs, along with enhanced consumer protection measures to safeguard seniors.